
Airbnb loans that qualify on booking income.
DSCR financing for Airbnb and VRBO rentals. The loan qualifies on the property's booking income, not your tax returns.
Up to 80% LTV. A market report works when there's no history yet.
Get your same-day term sheet
A few quick questions. No credit pull.
What is the loan for?
Tap one.
Program snapshot
- Max LTV
- 80%
- Income used
- Bookings or market report
- Booking history
- Not always needed
- Tax returns
- Not needed
- Foreign investors
- 70%
- Close in
- 30 days
What you get
- Qualify on booking income, not personal income
- 12 months of history or an AirDNA-style market report
- Some programs need no booking history
- Up to 80% LTV
- Single-family, condos and 2-4 units
- Close in your name or an LLC
Term sheet
Same day
Who it's for
- Buying a vacation rental to list on Airbnb or VRBO
- Refinancing a short-term rental with booking history
- Converting a long-term rental to short stays
- A foreign national buying a U.S. vacation rental
How Airbnb income qualifies
A short-term rental DSCR loan compares the property's booking income with its monthly payment (PITIA). Your personal income is not used.
An existing rental shows 12 months of booking history. A purchase or a new listing uses a short-term rental market report, such as AirDNA.
Some programs need no booking history at all.
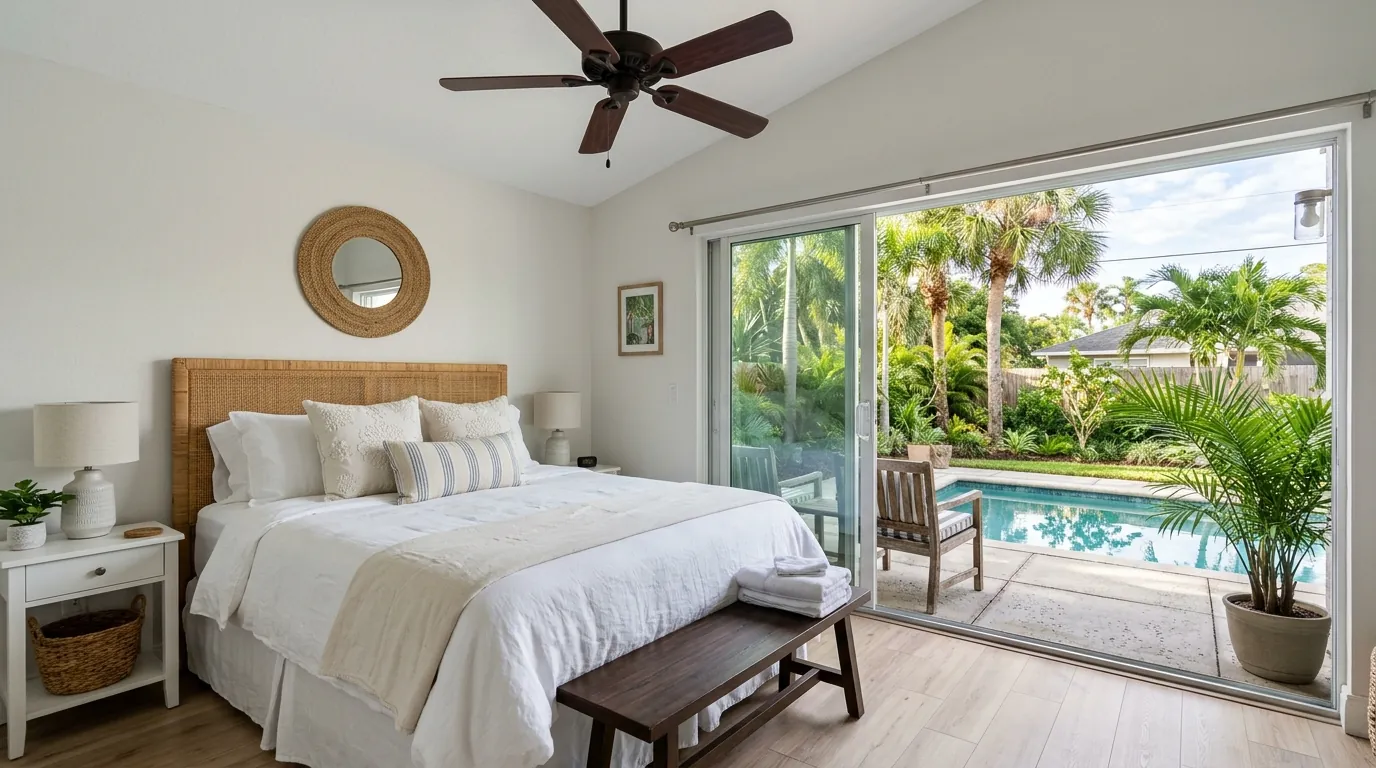
Booking history or a market report?
Booking history is what the property actually earned: 12 months of payouts from Airbnb, VRBO or a property manager. Twelve months covers every season, so slow months and peak months average out.
A market report estimates revenue from comparable listings nearby. AirDNA is the best-known provider.
It is the only option on a purchase or a new listing, and lenders often count it more conservatively than real history.
What to send
- Existing rental: 12 months of payout statements
- Purchase or new listing: a market report for the address
- The listing link, if it is live
- Property manager agreement, if you use one
Short-term rental DSCR example
Average monthly booking income of $4,200 against a $3,000 payment gives a DSCR of 1.40.
Best pricing starts at 0.8. Lenders go down to 0.75 with a pricing adjustment.
Run your own numbers in the DSCR calculator before you make an offer.
The numbers
- Average monthly booking income
- $4,200
- Monthly payment (PITIA)
- $3,000
- DSCR
- 1.40
Illustrative example. Subject to underwriting.
Costs to plan for
A short-term rental costs more to run than a long-term one. Furnishing, cleaning between stays, supplies, platform fees and management all come out of the bookings.
Many cities and states also charge occupancy or lodging taxes on each stay.
None of these are in the DSCR, which counts only the loan payment, taxes, insurance and HOA. Budget them separately before you buy.
Check local rules before you buy
Many cities limit short-term rentals with permits, minimum stays or zoning. Some ban them in certain neighborhoods.
Confirm the property can operate as a short-term rental before you sign.
From request to funded
Send the deal
Property, price and booking history or projected income.
Same-day term sheet
Rate, leverage and the income the lender uses. No hard credit pull.
Close in 30 days
Appraisal, title and closing.
Frequently asked questions
Can I get a DSCR loan on an Airbnb?
Yes. Short-term rentals qualify on booking income, not your personal income. Up to 80% LTV.
Do I need booking history?
Not always. An existing rental shows 12 months of history. A purchase uses a market report such as AirDNA, and some programs need no history.
What is AirDNA?
A market data company that estimates short-term rental revenue from comparable listings. Lenders use its reports when a property has no booking history.
How do seasonal markets qualify?
Twelve months of history covers every season, so slow and peak months average out. On a purchase, the market report already reflects the area's seasons.
Do I need a property manager?
Not always. Some lenders ask foreign owners for a U.S. property manager. Your term sheet says if one is required.
Is this for a vacation home I use myself?
No. These are business-purpose loans on investment property only, not a second home for your own use.
Can foreign nationals finance a short-term rental?
Yes. Up to 70% LTV, no SSN or U.S. credit required.
Can I close in an LLC?
Yes. Most short-term rental loans close in an LLC.
Sources
Related
Ready to price your deal?
Term sheet the same business day. No hard credit pull.